Porting a mortgage

What Is Porting a Mortgage?

Porting a mortgage means taking your existing mortgage deal with you when you move, so you keep the same interest rate and avoid the early repayment charge you would pay to leave it. You are not moving the loan itself. Your lender pays off the old mortgage on the sale and lends again on the new property, carrying the rate and the remaining deal period across.

I get asked about porting a mortgage by nearly every client who moves part way through a fixed rate. This guide covers how porting your mortgage works, what happens when you need to borrow more or less, the deadlines for getting a charge refunded, and when paying the charge is actually the better move. If you are earlier in the process, start with our moving home mortgages guide.

Jamie Alexander, CeMAP qualified mortgage adviser and director of Alexander Southwell Mortgage Services

Written by Jamie Alexander, CeMAP, Director and Mortgage and Protection Adviser with 15 years in mortgages. Reviewed October 2026.

Can I port my mortgage?

Porting Isn't Automatic: What Your Lender Checks

This is the bit that trips people up. "Portable" on your mortgage offer means you are allowed to ask. It does not mean the lender has to say yes. Porting a mortgage is a brand new application with the same lender, and your current mortgage history counts for less than people think.

Affordability, all over again

The lender looks at your household income and spending today, not what you earned when you first borrowed. A new car on finance, a baby, a drop in hours or a move to self employment all count. If you now work for yourself, our self employed mortgage guide covers what lenders want to see.

A valuation on the new home

The new property gets valued like any other purchase. If it comes in below the price you agreed, you may need a bigger deposit or a lower offer. Some lenders charge valuation fees on a port, many do not.

The property has to fit their criteria

Flats above shops, non standard construction, short leases and some new builds sit outside some lenders' rules. If your lender will not lend on the house you have found, you cannot port to it, however good your record is.

Your credit file

Expect a full credit search. Missed payments or new debts since your original mortgage can change the answer, so check your credit file before you apply.

The product must be portable

Most fixed rates and trackers are, but not all. Your original mortgage offer letter will say. If yours is not, porting is off the table and the charge applies.

Today's rules, not the old ones

Lenders change their lending criteria over time and you are judged on the rules they use now. A good mortgage broker will know which way your lender has moved before you apply.

Borrowing more

Porting and Borrowing More: Two Parts, Two Rates

Moving up the ladder usually means you need to borrow more money than the balance you are porting. The ported part keeps your current rate. The extra money is additional borrowing, and it goes on a new mortgage deal at whatever rate the lender offers movers today. So you end up with one mortgage in two parts. Say you port £200,000 at 2% and borrow another £60,000 at 4.5% (made up rates, just to show the maths). Your blended rate works out at about 2.58% across the whole £260,000. The catch is the end dates. Your ported part might have 18 months left while the new part is a fresh five year fix, and that can make your next remortgage awkward.

Advantages

+ Keep your existing rate on the ported balance

+ No early repayment charge on the part you move

+ One lender and one application

+ You can often pick the new part to finish when the old one does

Considerations

× Two parts can end on different dates

× The extra borrowing is priced at today's rates

× Small top ups can land on the lender's standard variable rate

× Full affordability checks on the total you need to borrow
Moving somewhere cheaper

Porting When You Downsize

If you are moving to a cheaper property and want a smaller mortgage, you can usually port part of it. The bit you pay off is treated as an early repayment, so you pay an early repayment charge on that amount only. Owe £250,000, need £150,000 on the new home, and the £100,000 you are not taking with you is what the charge is worked out on. At 3% that is £3,000. Some lenders, Nationwide for example, take any unused overpayment allowance off first. With a 10% allowance on £250,000, the charge would fall on £75,000 instead, so about £2,250. Check how your own lender does it before you agree a price.

Advantages

+ Only the reduced amount is charged, not the whole mortgage

+ Your overpayment allowance may cut the bill

+ Lower monthly payments on the new home

+ Equity from the sale stays with you

Considerations

× A partial early repayment charge is still a real cost

× Clearing the mortgage completely means the full charge

× You still have to pass the lender's checks

× Overpayment rules vary a lot between lenders

Jamie's view: For most people moving part way through a fixed rate, porting is the first thing I look at, because the charge for leaving early can run into thousands. But I never assume it is the answer. If your rate was fixed when rates were high, or the charge has nearly run down, paying it and moving to a new deal can work out cheaper. I run both sets of numbers before I recommend anything.

When to think twice

When Porting Doesn't Make Sense

Porting is a tool, not a rule. These are the situations where I often end up recommending something else, including the one where the lender makes the decision for you.

Your Rate Is No Longer Special

If you fixed at a high rate and better deals are around now, keeping that rate is not a prize. Pay the early repayment charge, take a new deal for the whole amount, and compare the total cost over the months you have left.

The Charge Is Small Or Nearly Gone

In the last year of a fix the charge is often 1% or less, and it disappears completely when the deal ends. If your move lines up with the end date, waiting a few weeks can mean a clean new deal with no charge at all.

The Lender Says No

A port is a fresh application. If your income has dropped, you have new credit, or the new home does not meet the lender's criteria, they can decline it. Then the realistic options are a purchase mortgage with a different lender and the charge paid, or timing the move for when your deal ends.

Before anything is submitted, I model porting, porting with a top up, and paying the charge to switch, side by side. You see the monthly payments, the charges and the total cost over the deal period for each, and you decide.

Early repayment charges

Early Repayment Charges Explained

An early repayment charge (ERC) is what your lender charges if you pay off more than your allowance, or leave the deal, before it ends. It is the whole reason porting a mortgage makes sense for so many movers, so it is worth knowing exactly what yours is.

How the charge is worked out

It is a percentage of the amount you repay, and on most deals it steps down each year. A common pattern on a five year fix is 5%, 4%, 3%, 2% and 1%. On a two year fix you might see 2% then 1%. Trackers and lifetime deals often have none at all.

On a £220,000 balance, 3% is £6,600. That is why the timing of your move matters so much. The same move six months later could cost you £2,200 less if the charge drops a step.

Where to find your figure

Your original mortgage offer letter, or the illustration that came with it, sets out the charges year by year. Your annual mortgage statement often shows them too. For the exact number on a given date, ask your lender for a redemption statement. It is usually free and it is the figure that actually gets charged.

Look for the exit fees as well. These are separate admin fees for closing the account, often a couple of hundred pounds or less, and they can apply even when there is no ERC.

The overpayment allowance

Most lenders let you overpay up to 10% a year without a charge. Use it before you move and you shrink the amount any charge is worked out on. Our overpayment calculator shows the effect.

When the charge ends

Once the deal period is over, the charge falls away. If your fix ends within a few months of moving, I will often look at a product transfer or a remortgage instead of porting.

Charged first, refunded later

If your sale completes before your purchase, many lenders take the full charge on the day you sell and refund the part you port once the new mortgage completes. You need the cash flow to cover that gap.

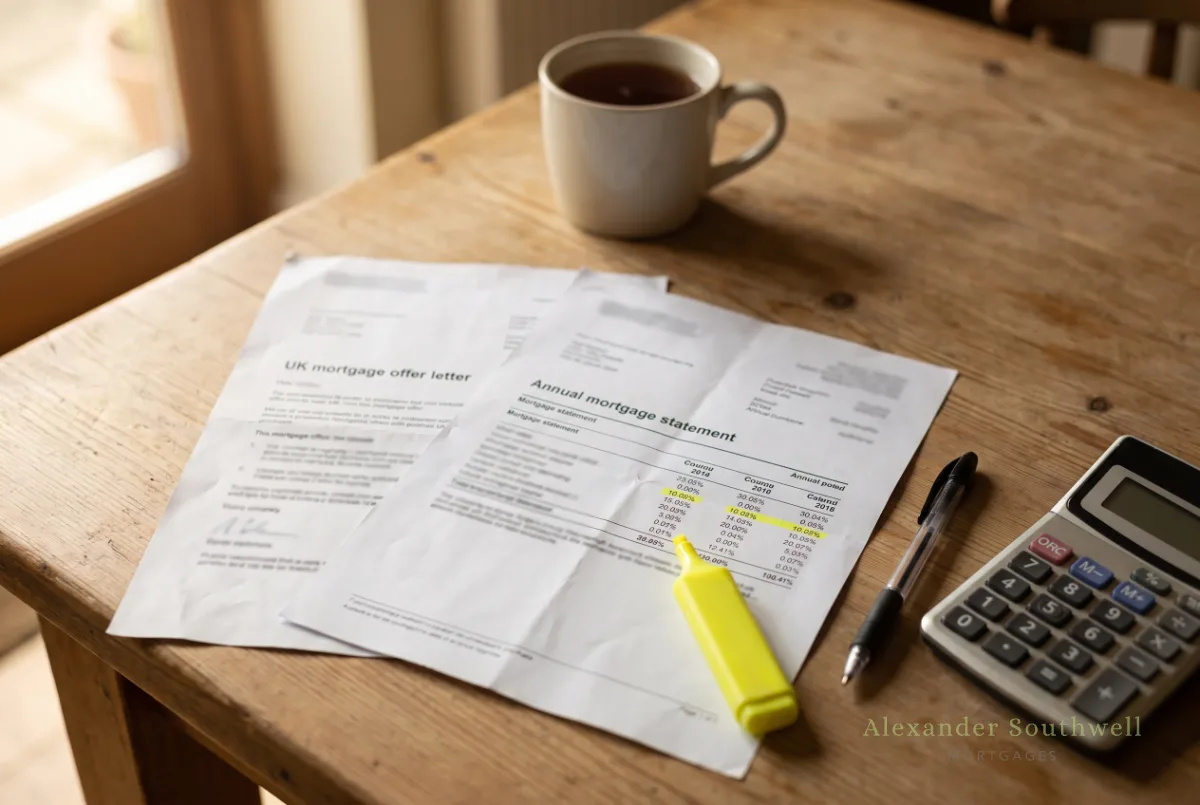
Mortgage offer and annual statement showing the early repayment charges table, used when porting a mortgage

Timing your move

The Porting Window: Selling and Buying on Different Days

In a perfect world you sell and buy on the same day and nothing is charged. Chains are rarely that tidy, and this is where porting a mortgage gets fiddly. If you sell first and rent or stay with family, most lenders give you a set window to complete on the new home and still get the charge back.

1

Same day completion

The old mortgage is paid off and the new one starts on the same day. No early repayment charge is taken on the part you port. This is the cleanest way to do it.

2

Sell first, buy later

The lender usually takes the full charge when your sale completes, then refunds the ported part if you complete your purchase inside its window. Miss the deadline and the refund is gone.

3

Buy first, sell later

Harder. You would need the lender to let you hold two properties for a while, or a bridging loan, and the port happens when the sale goes through. Speak to me before you commit to this.

How long you get

It varies by lender. At the time of writing, NatWest gives a maximum of 4 months from redemption, Yorkshire Building Society gives 6 months, and Nationwide allows up to 180 days in some cases. Policies change, so always check your own lender's current rules.

Watch your offer date

A mortgage offer has its own expiry date, often around six months. A long gap between selling and buying can mean the offer runs out and the case has to be reassessed.

Keep the paperwork

Hold on to your redemption statement and completion statement. If a refund is due it normally goes back through your solicitor, and you want the figures to match.

Removal boxes and house keys in a hallway on moving day, when porting a mortgage between sale and purchase

Worked example

Porting vs Paying the ERC: Two Real Looking Cases

These are the two conversations about porting a mortgage I have most often. The rates are made up to show the maths, not today's rates, and both assume 25 years left on a repayment mortgage.

Case 1: Porting wins easily

Priya and Sam owe £220,000 on a fix at 2% with 24 months left. Their ERC is 3%, so £6,600. The best new deal they could get is 4.5% with a £999 fee.

Over those 24 months, the new deal would cost them about £10,800 more in interest. Add the charge and the fee and switching costs roughly £18,400 more than porting the mortgage they already have. Easy call: they port, and borrow the extra they need as a second part.

Case 2: Paying the charge wins

Dan owes £180,000 on a fix he took at 6.1%, with 30 months left and a 3% charge of £5,400. He could get a new deal at 4.2% with a £999 fee.

The lower rate saves him about £8,500 in interest over those 30 months. Take off the £5,400 charge and the fee and he is still around £2,100 better off paying the ERC and switching. Porting would have kept him on the more expensive rate.

The lesson: a big charge does not automatically mean you should port. Compare the total cost over the months you have left, including fees, before you decide.

Calculator

Porting vs ERC Calculator

Put in the numbers from your current mortgage to see the early repayment charge, the interest you would save or lose on a new deal over the months you have left, and which way the numbers lean. For the full cost of moving, use our moving home calculator too.

ERC to leave
£0
On the balance after any allowance
Interest if you port
£0
Monthly payment £0
Interest on a new deal
£0
Monthly payment £0
Net difference
£0
Over the months left

For illustration only and not financial advice. Assumes a capital and interest mortgage, fixed rates for the whole period and the same balance either way. It ignores product fees on your current deal, any extra borrowing, valuation and legal fees, exit fees and whether you would pass a new lender's checks. Use the exact charge from your redemption statement and a rate you could actually get. Your home may be repossessed if you do not keep up repayments on your mortgage.

More questions

Porting a Mortgage: More Questions Answered

How long does it take to port a mortgage?

Porting a mortgage takes about as long as a new purchase mortgage. Once the application is in, an offer typically takes two to four weeks, longer if the valuation or paperwork is slow. Start as soon as you have an offer accepted on the new home.

Is there a fee to port a mortgage?

Some lenders charge nothing to port. Yorkshire Building Society, for example, says there is no porting fee. You may still pay a product fee on any extra borrowing, plus valuation and legal fees on the purchase.

What happens if my sale falls through?

Nothing changes on your current mortgage. You stay on the same deal at the same rate until you find another buyer, and the port goes ahead when you do, as long as your deal has not ended.

Can I port if I am on my lender's standard variable rate?

There is nothing to port. A standard variable rate has no early repayment charge, so you are free to take any new deal for the move, and you should.

Can I add or remove someone when I port?

Often yes, but it is treated as a new application for whoever will be on the new mortgage. Coming off a joint mortgage means you need to afford it alone, and a new partner joins the affordability and credit checks.

Related guides and tools

Your home may be repossessed if you do not keep up repayments on your mortgage. There may be a fee for mortgage advice: we are fee free on over 90% of cases, charge £299 on mortgages under £100,000, and complex or adverse cases can carry a fee of up to £995. Alexander Southwell Mortgage Services Ltd is authorised and regulated by the Financial Conduct Authority (FCA no. 1011890).

Can I port my mortgage to a new house?

Is it better to port my mortgage or pay the early repayment charge?

How much is an early repayment charge?

Can I port my mortgage to a different lender?

Do I need a new mortgage application to port?

Worked example

Porting Your Mortgage: The Numbers Side by Side

The easiest way to see whether porting your mortgage is worth it is to run the numbers both ways. These figures are made up for illustration, but they are the same sums we do for every client.

Your existing mortgage

Say your current mortgage balance is £180,000 on a fixed rate with two years left, and your existing lender charges a 3% early repayment charge. Paying off the existing mortgage now would cost £5,400 on top of everything else.

Porting and borrowing more

You are buying a £400,000 home and need £250,000. Porting keeps the £180,000 on your existing rate, and the extra £70,000 is additional borrowing on a new mortgage rate from the same lender. No early repayment charge, but two parts to manage.

Moving to a new lender

Or you pay the £5,400 charge and take one new mortgage deal for £250,000 with a different lender. If that mortgage rate is low enough, the saving over the deal can outweigh the charge. We compare both before you decide.

We are fee free on over 90% of cases. Where a fee does apply, it is £299 on mortgages under £100,000 or up to £995 on more complex or adverse cases, and we always tell you before any work starts.

Your home may be repossessed if you do not keep up repayments on your mortgage.