Eastleigh is about 15 minutes from our Romsey office, so a lot of the people we help live here or are trying to buy here. The questions are nearly always the same: how much can I borrow, which lender will say yes, and what happens next. Here are straight answers, plus the local bits that change the outcome.
Where people are buying in Eastleigh
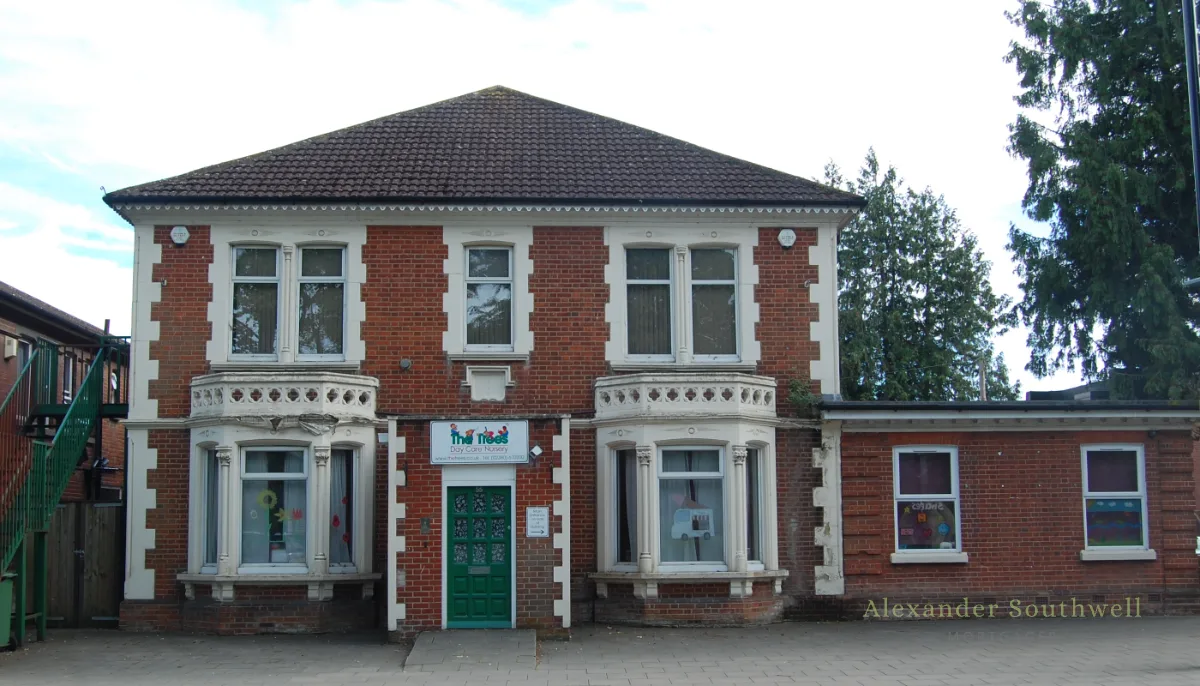
The town grew up around the railway. The carriage works moved here from Nine Elms in 1891 and the locomotive works followed in 1909, and many of the terraced streets near the station and off Leigh Road were built for the families who worked there. Those two and three bed terraces are still where a lot of our first time buyers start.
Chandler's Ford is the pricier end of the borough, with bigger semis and detached homes and plenty of families moving in for the schools. Bishopstoke, Fair Oak and Boyatt Wood have lots of 1960s to 1980s semis that make a sensible second step. Hedge End and West End suit anyone who needs the M27 every day.
Older terraces can come back from the valuation with damp or an extension with no paperwork, and some former council homes need a lender that is comfortable with them. Knowing which lenders are relaxed about what saves wasted applications.
First time buyers: a worked example
The ONS puts the average first time buyer price in Eastleigh at £252,000 (July 2026). With a 10% deposit of £25,200, that leaves a mortgage of £226,800. Many lenders cap borrowing at around 4.5 times income, so you would typically need a household income of about £50,400. Some lenders go higher for bigger earners.
On a repayment mortgage over 30 years, an illustrative rate of 4.5% works out at about £1,149 a month. At 5% it is about £1,218. Over 35 years at 4.5% it drops to around £1,073, but you pay more interest overall. These are examples, not quotes.
Stamp duty on that purchase would be £0, because first time buyers in England pay nothing on the first £300,000. Check your own figures with our stamp duty calculator, and if you are just starting out, our first time buyer mortgages guide covers the rest.
Buying with a 5% deposit
You can still buy in Eastleigh with 5% down. On the same £252,000 home that is a £12,600 deposit and a £239,400 mortgage, or about £1,213 a month over 30 years at 4.5%, again purely as an illustration.
The catch is choice. Fewer lenders lend at 95%, the rates are higher, and some cap new build flats at a lower loan to value. Our 5% deposit mortgages page explains how to give yourself the best chance.
New build homes around Eastleigh
The borough has been building a lot. Boorley Gardens at Boorley Green and Stoneham Park are two of the bigger sites, with smaller developments around Fair Oak and Horton Heath.
New builds come with their own rules. Some lenders limit how much they will lend on a new build flat, offers can run out before the build is finished, and any developer incentive has to be declared. Read our new build mortgages guide before you pay a reservation fee, not after.
Commuting, shifts and overtime
Transport is a big reason people pick Eastleigh. Eastleigh station and Southampton Airport Parkway both have direct trains to London Waterloo, and the M3 and M27 meet right on the edge of town.
It is popular with commuters and with shift workers at the airport, the rail depot and the hospitals in Southampton and Winchester. Lenders treat overtime and shift pay very differently. Some use most of it, others only count half, and on £8,000 of overtime that gap can be worth £36,000 of borrowing.
Remortgaging, moving and downsizing
If your fixed rate ends in the next six months, talk to us now. Your lender will usually offer a product transfer, and sometimes that is the right answer. We compare it with the market and time the switch so you do not drift onto the standard variable rate. Our remortgage advice page has more.
Moving up to Chandler's Ford is common, and so is the reverse, with downsizers selling the family home for something smaller. Our moving home mortgages page covers porting and borrowing more.
Buy to let in Eastleigh
The ONS puts the average private rent in Eastleigh at £1,214 a month (August 2026), up 3.4% in a year. Lenders want the rent to cover the payment by a margin at a stressed rate, often around 125% to 145%.
We arrange buy to let mortgages for first time landlords and portfolio landlords, including limited company purchases. Most buy to let mortgages are not regulated by the FCA.
Protecting the home once you have it
You will need buildings insurance in place by completion, and on a freehold house it is usually your responsibility from exchange. Life cover and income protection deserve a proper look too, especially if one salary pays most of the mortgage.
We can go through mortgage protection and home insurance alongside the mortgage, with no pressure to take anything.

Checking who you are dealing with
Any mortgage broker you use in Eastleigh should be on the FCA register. It shows whether a firm is directly authorised or an appointed representative of a network, and what it is allowed to do. Our firm reference number is 1011890.
It is fair to ask how a broker gets paid. We are fee free on over 90% of cases, because the lender pays us. There is a £299 fee on mortgages under £100,000, and complex or adverse credit cases can carry a fee of up to £995, always agreed in writing before any work starts. You can see what other clients say on our reviews page.
How far is your office from Eastleigh?
Our office is at NIX Business Centre in Romsey, about 15 minutes' drive away. Plenty of clients never visit and do everything by phone, video call and WhatsApp.
How much can I borrow on my salary?
Most lenders work on around 4 to 4.5 times income, and some go to 5 times or a little more for higher earners or certain professions. The calculator below gives a quick guide, and an Agreement in Principle firms it up.
How long does getting a mortgage take?
An Agreement in Principle can often be done the same day. Application to mortgage offer usually takes two to four weeks, and the whole purchase is more often 12 to 16 weeks.
What if I have had credit problems?
Missed payments, defaults or a CCJ do not automatically rule you out, but they shorten the list of lenders. The first job is to see your credit file the way lenders see it. Our Check My File guide explains how.
Do I need a survey as well as the valuation?
The lender's valuation is for the lender, not for you. On older Eastleigh terraces, or anything that has been extended or altered, a RICS Level 2 or Level 3 survey is usually money well spent.
Can family help with my deposit?
Yes. Most lenders accept a gifted deposit from family, with a signed gift letter and proof of where the money came from. Some families help in other ways, such as a guarantor mortgage or a joint borrower sole proprietor mortgage.
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.