
I'm Jamie Alexander. I've worked in mortgages for 15 years and set up the firm in 2019. Our office is in Romsey, just over the border in Hampshire, and we help people from Christchurch to Lyme Regis by phone, video and email. You get the same broker from the first call to the day you get the keys, and we keep in touch when your deal comes up for renewal.

We help buyers and homeowners across the whole county, from the conurbation in the east to the Jurassic Coast in the west. Bournemouth has its own page with local prices and areas.
The biggest town in the county, with seafront flats, family homes in Southbourne and big employers including JP Morgan.
From harbourside apartments to family homes in Parkstone and Broadstone, with some of the most expensive streets on the south coast.
Older houses, bungalows and harbour views. Popular with downsizers, with some homes near the water where flood risk is worth checking.
The county town, on the main line to London Waterloo, with Poundbury's newer homes on its western edge.
More affordable coastal homes at the end of the line from Waterloo, popular with first time buyers and people moving to the sea.
Commuter towns for Bournemouth and Poole, with plenty of family houses and bungalows.
North Dorset towns on the line between London Waterloo and Exeter, with period homes in Sherborne and newer estates in Gillingham.
Stone cottages, coastal homes and a lot of second homes. Lovely places to live, with a few extra lender checks.
Not on the list? We also help buyers in Bridport, Lyme Regis, Blandford Forum, Verwood, Shaftesbury and the villages in between. Just contact us and tell us where you are looking.
Dorset is split between two councils for the official figures. Dorset Council covers most of the county, while Bournemouth, Christchurch and Poole are reported together.
In the Dorset Council area, detached homes averaged £515,000, semi detached £330,000, terraced £265,000 and flats £167,000. Prices were flat over the year at 0.1%, while the BCP area fell by 1.9%. On the Dorset Council average, a 5% deposit is about £16,250 and a 10% deposit about £32,500, before solicitor fees, a survey and any stamp duty.
A worked example: a first home in Weymouth
Take a couple buying a terraced house in Weymouth for £265,000, the Dorset Council average for that type of home. With a 10% deposit of £26,500 they would borrow £238,500. Many lenders cap borrowing at around 4.5 times income, which points to a joint income of about £53,000. Over 30 years at an illustrative 4.5% rate, the monthly payment would be about £1,208. That is an example, not a quote, and your own figures depend on your credit file, outgoings and the deal on offer.
Source: UK House Price Index (HM Land Registry and ONS), July 2026; ONS Price Index of Private Rents, August 2026.

The east of the county
Bournemouth, Poole and Christchurch have their own jobs market, so many buyers there never commute far. The fastest trains from Bournemouth reach London Waterloo in about 1 hour 47 minutes, and the A31 and A338 link the area to the M27.
Dorchester, Weymouth and the main line
The South West Main Line runs through Poole, Wareham and Dorchester to Weymouth, and the Heart of Wessex line heads north to Bristol. That makes the county town a good base for people who split their week.
North Dorset
Sherborne and Gillingham are on the line between Waterloo and Exeter, with Yeovil just over the border. Blandford and Shaftesbury suit people who drive, with the A350 and A354 running north towards Salisbury.
The coast and the countryside
From Purbeck to Lyme Regis, the Jurassic Coast is one of the most beautiful stretches in the country. Homes here often need a closer look from lenders, which is where good mortgage advice earns its keep.
Most Dorset mortgages are straightforward. A few features of the county come up again and again, and they change which lenders we use.
The Jurassic Coast runs for about 155 km, and some clifftop and seafront homes carry erosion or flood risk. Lenders and insurers check this closely, so we look at the reports before you offer.
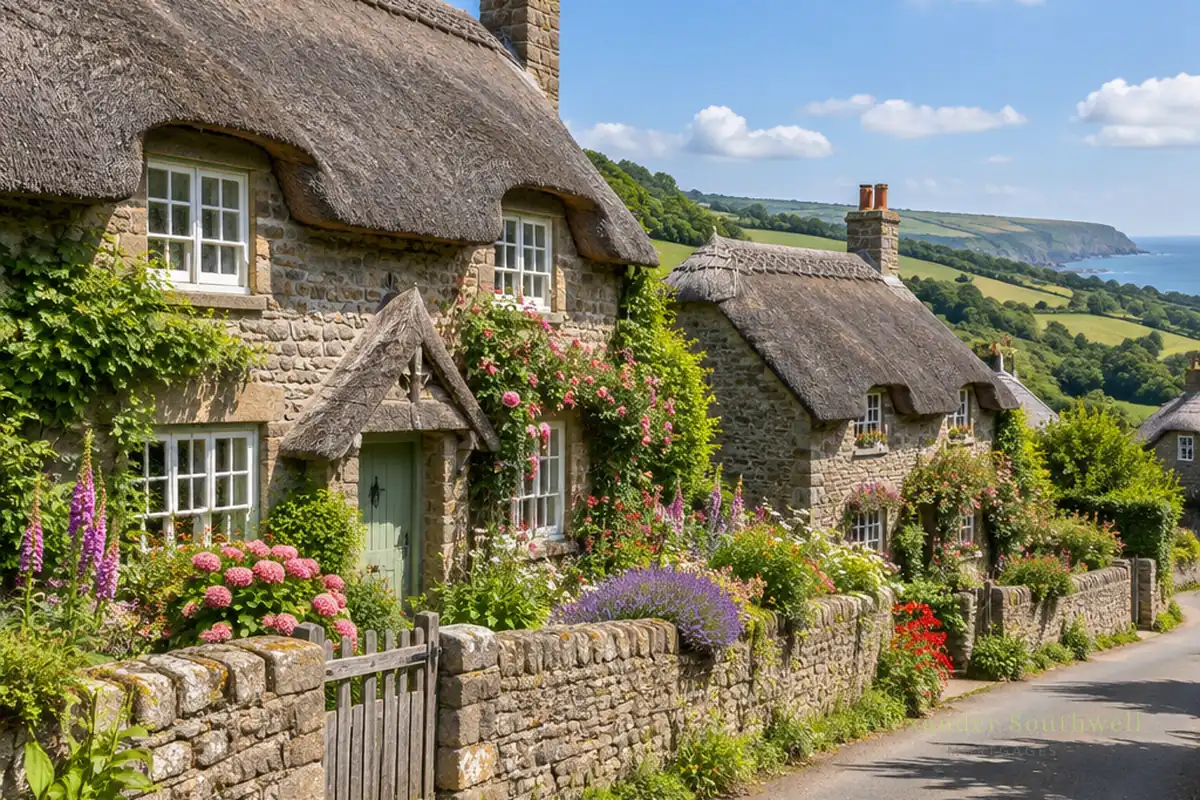
Stone cottages and thatched roofs are part of what makes the county special. Thatch insurance has risen sharply, and some lenders are cautious with non standard construction, so we pick lenders that are comfortable with them.
Dorset Council has charged double council tax on second homes since April 2025. Second homes and holiday lets need different mortgages from a normal home, often with a larger deposit.
More than a third of homes in the BCP area are flats. Lenders check the lease length, ground rent, service charge and, on some blocks, fire safety paperwork such as an EWS1 form.
Dorset has a high share of older homeowners. We help with mortgages for downsizers and retirement interest only mortgages, and we refer equity release to a trusted specialist firm.
Alexander Southwell Mortgage Services Ltd is directly authorised and regulated by the Financial Conduct Authority, firm reference 1011890. Our trading styles include Alexander Southwell Mortgages and The Fee Free Mortgage Broker. If you ever have a complaint we will look into it properly, and if you are not happy with our answer you can refer it to the Financial Ombudsman Service.
Buying a home or switching your mortgage can be stressful, and a lot of that stress comes from not knowing what happens next. This is how we handle it.
Before we look at a single rate, we talk through your income, your plans and how long you expect to stay. That shapes the right deal far more than the headline rate does.
We compare lenders across the market, including deals you will not find on the high street, and explain why we are recommending one in plain English.
We package the application properly, chase the lender, the valuer and the solicitors, and keep you updated at every step so nothing goes quiet.
Once your offer is in, we talk you through life cover, critical illness cover and income protection. There is no obligation, but we always raise it.
Most of our clients come to us through recommendation, and our 193 five star Google reviews say the same things again and again: we are easy to understand, we answer the phone and we explain things clearly.
From working out what you could borrow to getting the mortgage offer, with every step of the mortgage process explained in plain English.
Porting your current deal, borrowing more or starting again with a new lender. We work out which costs less once early repayment charges are counted.
We start looking up to six months before your current deal ends and compare a product transfer with the rest of the market. Remortgages are always fee free with us.
For landlords buying or remortgaging, in your own name or through a limited company. Lenders look at the rental income as well as your own income.
Sole traders, company directors and contractors. We know which lenders will use your latest year of figures and which want an average of two.
Missed payments, defaults or a CCJ do not always rule you out. We start by going through your credit file with you before anything is applied for.
Tight exchange deadlines, developer incentives and the extra checks lenders run on brand new homes. I spent four years as a specialist new build broker.
Life cover, critical illness cover and income protection, so the mortgage still gets paid if life takes a turn. Our protection advice is whole of market.
Written by Jamie Alexander, CeMAP qualified mortgage adviser and director of AS Mortgages
Jamie has 15 years in mortgages and founded the firm in 2019. The team has submitted over 2,500 mortgage applications and has well over 20 years of combined experience. Alexander Southwell Mortgage Services is authorised and regulated by the Financial Conduct Authority, firm reference 1011890. More about Jamie .
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home.
From your initial consultation to when your mortgage completes we manage the whole process for you. We coordinate with estate agents and solicitors where necessary to keep everyone moving towards your completion date.
A free, no obligation phone or video call to discuss your goals, deposit, income, credit history and the area of Dorset you are buying in. This gives us everything we need to start searching the whole market for the right mortgage for you.
Your adviser will compare mortgage products across suitable lenders and prepare a tailored recommendation. You’ll receive an Illustration (ESIS) showing the interest rate, fees and total cost over the mortgage term so you can make an informed decision.
We can often get a Decision in Principle (DIP) the same day or within 24 hours. This is essential when making offers on properties in popular Dorset locations like Bournemouth and Poole where competition from buyers can be fierce.
We’ll handle the paperwork, submit your documents to the lender, liaise on your behalf and arrange the valuation or survey. You won’t need to chase: we do that for you.
We’ll track your case through underwriting, chase solicitors and other parties if needed and keep you updated through to exchange and completion. Once you’ve got your keys we’ll diarise a review before any fixed rate ends so you’re never left on an expensive standard variable rate.


Yes, through lenders that offer second home mortgages. They assess your income and existing mortgage together. Dorset Council has charged double council tax on second homes since April 2025, so factor that into your budget.
Yes. Holiday let mortgages are assessed on the expected holiday income rather than a long term rent, and many lenders want a larger deposit. Tell us early so we can check the numbers.
Equity release is a specialist area, so we refer it to a trusted specialist firm. We can talk through the alternatives first, such as downsizing or a retirement interest only mortgage.
Sometimes the deal from your existing lender is the best option and sometimes it is not. We compare both and tell you which costs less overall. Remortgages are always fee free with us.
Yes. Our office is at NIX Business Centre, 2 Park Court, Romsey SO51 9DH. It is a shared office building, so please book ahead. Most clients find phone and video easier.


