
Equity is the part of your home you own outright: its value minus the amount you owe. If your home is worth £350,000 and your outstanding mortgage balance is £200,000, you have £150,000 of equity. When you remortgage to release equity, you take out a new, larger mortgage, pay off the old one and receive the difference as a lump sum.
Most homeowners do this when their fixed rate is ending, so there are no early repayment charges to pay. You can also borrow more from your existing lender, which I cover further down. Either way your monthly payments will usually go up, so we work out the new figure with you before you commit to anything.
How much can you release?
Two things decide how much equity you can release: the lender's loan to value limit, and if your income can support the bigger mortgage. You need to pass both. Plenty of homeowners have lots of equity but not enough income.
The loan to value limit
Loan to value, or LTV, is your new mortgage as a percentage of the value of your home. Most lenders will let you borrow up to 85% of the property value when you raise money, and a few go to 90% for things like home improvements. Debt consolidation and anything unusual is usually capped lower. Our loan to value calculator shows which band you sit in.
Affordability checks
The lender looks at your income, outgoings, credit file and other debts. Most lend around 4 to 4.5 times income and stress test the payment at a higher rate. If the numbers do not work, the equity in your house does not matter.
The value of your home
The lender's valuer decides what your home is worth, not the website you checked last night. A low valuation means less to release. I always build in a margin for this. Your age matters too: lenders want the mortgage repaid by around 70 to 75, so a shorter term in your fifties can limit what you can borrow.
Typical maximum LTV by what the money is for
| Purpose of the extra borrowing | Typical maximum LTV | What lenders look for |
|---|---|---|
| Home improvements | 85%, some lenders 90% | A rough schedule of works or quotes on bigger jobs |
| Gifting a deposit to family | Usually 85% | Who the money is for and that it is a gift, not a loan |
| Buying a second home or buy to let | Usually 75% to 85% | Details of the purchase and how the new mortgage will be paid |
| Paying off other debts | Often 75% to 85% | Exactly which debts, and they are often paid off directly |
| Business purposes | Limited choice, often lower | Many high street lenders will not lend for this at all |
| Interest only on the extra borrowing | Often 50% to 75% | A clear plan to repay the capital at the end |
Typical ranges I see across the market, not promises. Lender rules change often.
Calculator
Put in what your home is worth, what you owe and the LTV you want to borrow up to. The calculator shows how much equity you could release and what the new monthly payment might look like at the interest rate you choose to test.
Worked example
Real numbers make this much clearer. The rate here is for illustration only. It is not a current rate and it is not a quote.
Mark and Claire live just outside Romsey. Their home is worth around £350,000 and they owe £180,000 with 20 years left. Their daughter has found a flat and needs £40,000 for a deposit, so they want to remortgage to release equity and gift it to her.
Before: £180,000 over 20 years
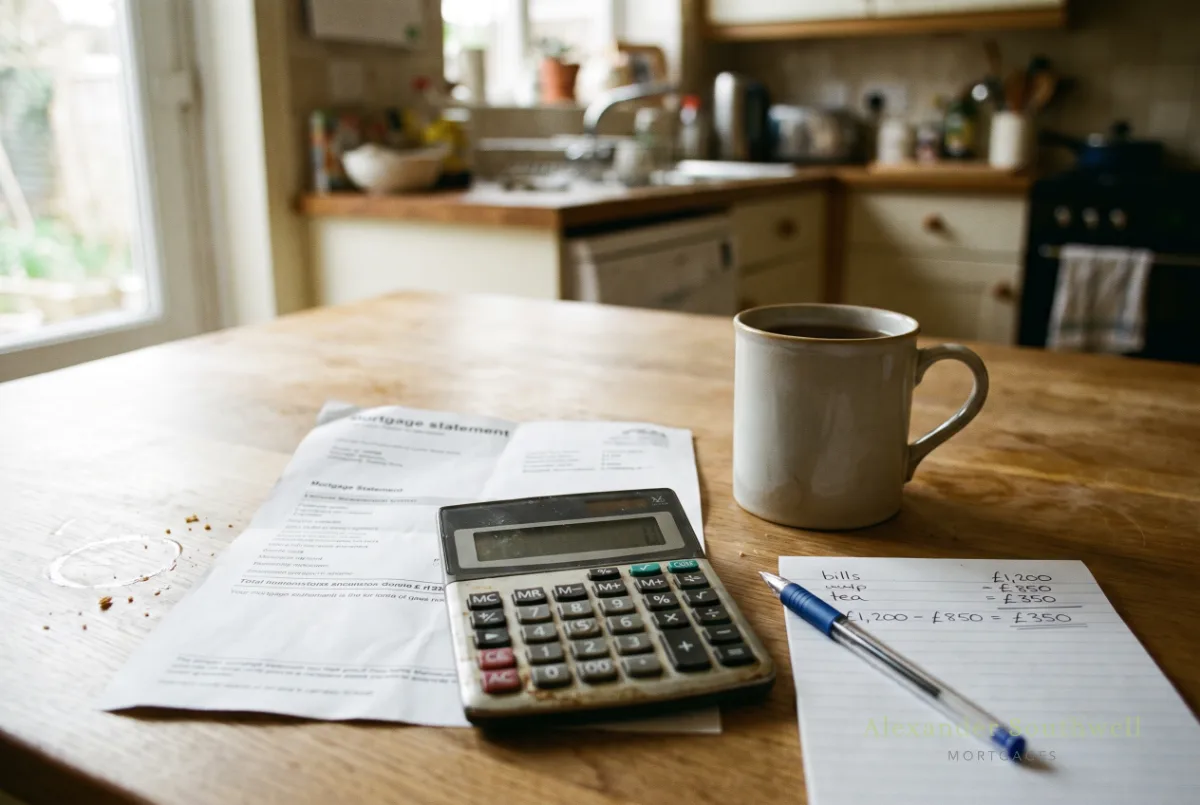
LTV about 51%. At an illustrative 4.5% the monthly payment is about £1,139. Total interest over the 20 years is about £93,300.
After: £220,000 over 20 years
LTV about 63%. At the same rate the payment rises to about £1,392, so £253 more each month. Total interest is about £114,000, so the £40,000 costs them roughly £20,700 in interest.
The trap with a longer term. If they stretched the new mortgage to 30 years, the payment would drop to about £1,115, which is actually less than they pay now. Sounds great. But the total interest would be about £181,300, nearly £88,000 more than if they had left things alone. This is the bit that trips people up, and it is why I always show the full cost, not just the monthly figure.
For comparison, a £40,000 personal loan over five years at an illustrative 7% would cost about £792 a month but only around £7,500 in interest. Higher payments, far cheaper overall. Neither is right for everyone, which is why we look at both.
Their new LTV is well under 75%, so pricing stays good. At 85% the rate would likely be higher, and that changes the sums.
Common reasons
Lenders do not mind too much what you spend the money on, but they do ask, and some purposes get better terms than others. These are the reasons homeowners give me most often.
Home improvements
The classic reason to raise money, and lenders like it because the work can add value to their security. If that is your plan, our remortgage for home improvements page covers it properly.
Helping your children onto the ladder
Gifting a deposit is now one of the biggest reasons people come to us. Your child's lender will want a letter confirming it is a gift, not a loan. If you would rather not hand over cash, a guarantor mortgage or a joint borrower sole proprietor mortgage can work instead. Our bank of mum and dad guide compares the options.
Buying a second home or buy to let
Common, but it means two mortgages to pay. For a buy to let investment the rent has to stack up for the new lender, and higher rate stamp duty applies. Our buy to let mortgages page explains how lenders assess the rental side.
Paying off other debts
Moving credit cards and loans onto your mortgage can cut your monthly outgoings, but spreading short term debt over a long mortgage term can mean you pay more in total. Think carefully before securing other debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage. Read our debt consolidation remortgage page before you decide.
Business purposes
This is where lenders get twitchy. Many will not lend for business purposes at all, and the rest usually want a lower LTV. You are also putting your home behind a business risk, so business finance is often the better route.
Other large purchases
Weddings, a car or school fees are usually accepted, though some lenders cap the amount. Borrowing for a car over 25 years rarely makes sense, and I will tell you if a cheaper option exists.
Paying a divorce settlement
If you are keeping the house after a divorce or separation, you may need to raise money to pay your ex their share and move the mortgage into your sole name. The lender looks at your income alone, and usually wants to see the financial settlement or the solicitor's draft. Talk to us before the figure is agreed, so you know what you can actually borrow.
Uses some lenders do not like
Some lenders will not lend to pay a tax bill, buy property abroad or invest in shares or crypto, and others only do it at a lower LTV. Anything speculative is usually a no. Be upfront about the purpose. It is far easier to pick the right lender at the start than to have a case declined at underwriting.
Same lender or new lender?
There are three ways to release equity from your home with a mortgage. You can ask your existing lender to lend you more, move the whole mortgage to a new lender, or take a second charge loan on top. The right one depends mostly on where you are in your current deal.
Your current lender lends you the extra on a separate sub account. Your existing deal stays in place, so no early repayment charges, and it is often quicker with no legal work. The catch: you only see one lender's rates, and they are not always competitive.
You replace your whole mortgage with a new mortgage, borrowing more at the same time. You get the whole market and often a lower interest rate on the full amount. But early repayment charges can wipe out the saving if you are mid fix, and it typically takes four to eight weeks.
A separate loan secured on your home behind your existing mortgage, usually from a different lender. Your current deal stays untouched, which can make sense if you are on a very low fixed rate or facing a big early repayment charge. Rates are usually higher than on a first mortgage, there can be extra fees, and it is still debt secured on your home. Worth comparing when neither of the other two fits.
My rule of thumb: if your fixed rate ends within the next six months or so, a full remortgage usually wins. If you are two years into a five year fix, a further advance is often cheaper. We compare both and show you the numbers side by side. Our guide to product transfer vs remortgage covers staying or moving, and remortgage options explained sets out the other routes.
Fees and charges
The interest is the big one, but there are other fees to factor in before you decide it is worth it. Here is what to expect.
Early repayment charges
If you leave a fixed rate early, your current lender may charge an early repayment charge, often 1% to 5% of the balance. On a £200,000 mortgage that could be several thousand pounds. Always check your current mortgage deal end date first.
Arrangement fees
Many deals have a product fee of around £999, some none at all. A lower rate with a fee is not always cheaper than a higher rate without one, especially on smaller loans.
Valuation and legal work
Most remortgage deals include the valuation and legal work at no cost. A further advance may need neither. If you need a specialist lender, you might pay for these yourself.
Our fee
We are fee free on over 90% of the cases we handle. We charge £299 on mortgages under £100,000, and complex or adverse cases can carry a fee of up to £995. You will know in writing before we start. More on how we work is on our fee free remortgage broker page.
For a full breakdown with examples, see remortgage costs explained.
Think it through
Releasing equity can be a sensible move, but you are adding to the debt secured on your home. I would rather you go in with your eyes open, so here are the downsides.
Higher LTV means higher rates
Rates are priced in LTV bands, usually every 5%. Tip into a higher band and the rate can rise on the whole mortgage, not just the extra bit. Sometimes releasing £5,000 less saves more than it costs.
Longer terms cost more
A longer mortgage term keeps monthly repayments down but you pay interest for longer, as the example above shows. It can also push the mortgage into retirement.
Negative equity
If house prices fall after you borrow more, you could owe more than your home is worth. That is negative equity, and it can trap you with your current lender when your deal ends. The higher your LTV, the smaller the cushion.
The debt is secured on your home
Unlike personal loans, missed payments on your mortgage put your home at risk. Make sure the new payment still fits if your income drops or rates rise when your next deal ends.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Interest only
Sometimes, but it is tightly restricted. Taking the extra borrowing on interest only keeps the monthly payment down because you only pay the interest, but the capital is still owed in full at the end of the term.
What lenders want to see
Many lenders will not allow interest only for capital raising at all. Those that do usually want a lower LTV, plenty of equity left and a credible repayment plan such as investments, pensions or selling another property.
Part and part
A middle ground is part and part: keep your existing mortgage on repayment and put only the new borrowing on interest only. You still need a real plan for that lump sum. Hoping to downsize one day is not usually enough.
Over 55?
People search for equity release when they mean a remortgage, and the other way round, so it is worth being clear. They are very different products.
A normal mortgage. You make monthly payments, the lender checks your income, and the loan is repaid over a set term. This is what we arrange, and it suits people who can comfortably afford the payments.
Equity release usually means a lifetime mortgage, for homeowners aged 55 and over. You often make no monthly payments, interest rolls up, and the loan is repaid when you die or move into long term care. That reduces any inheritance you leave to loved ones.
AS Mortgages does not advise on equity release or lifetime mortgages. If that sounds like what you need, we can point you to a specialist equity release adviser. If you are in later life with a good pension or still working, a standard remortgage may still be possible, and we are happy to look.
Here is how the remortgage process usually runs with us, from the first call to the money landing in your account. Most cases take four to eight weeks.
A free chat about how much you want to raise, what it is for and what your home might be worth. I check if a further advance or a new lender makes more sense.
We get an agreement in principle from the most suitable lender, often with a soft credit search, so you know where you stand before applying.
The lender values your home. This sets the loan to value and the amount you can release, so we plan around a cautious figure.
We submit the full application with your payslips or accounts, bank statements, ID and your latest mortgage statement.
The lender issues a formal mortgage offer. We check it matches what was agreed and talk you through it before you accept.
The solicitor pays off your old lender and sends the released equity to your bank account, usually on the day the new mortgage starts.
Want to know how much you could release? Call 03300 432 428 or book a free chat and we will run the numbers with you. No obligation.
Frequently asked questions
Most lenders go up to 85% of your home's value when you raise money, a few to 90% for home improvements. Take off your current mortgage balance to get the most you could release. Your income must also support the bigger mortgage.
Most lenders want at least 10% to 15% equity left after you borrow more, so you need to own more than that to release anything. The more equity you keep, the better the rates tend to be.
It can be, for home improvements or helping family, if the new payments are comfortable. For small amounts or short term spending a personal loan may cost less overall. Look at the total interest, not just the monthly payment.
For smaller amounts a personal loan is often cheaper overall and is not secured on your home. A second charge mortgage can work if you want to keep a very low fixed rate. Downsizing or using savings avoids new debt altogether. Our remortgage options explained page sets out the wider choices.
Yes. You can ask your existing lender for a further advance, which avoids early repayment charges, or remortgage to a new lender and pay the charge if the numbers still work.
Sometimes. Missed payments or defaults limit your choice of lender and the maximum LTV, and rates are usually higher. Specialist lenders may help. See our bad credit mortgage broker page for more.
No. Equity release usually means a lifetime mortgage for over 55s, where interest often rolls up. A remortgage is a normal mortgage with monthly payments. We do not advise on equity release, but we can point you to a specialist.
No, money you borrow is not income, so there is no income tax on it. If you gift it to family, gifts can affect inheritance tax in some cases, so it is worth checking with a financial adviser or accountant.
Most lenders want you to have owned the property for at least six months before they will let you raise money on it, and some want longer. If the value has gone up because of work you have done, the lender will rely on its own valuation, not your estimate. If you are still inside an early repayment charge period, the cost of leaving usually decides the timing anyway.
A remortgage to a new lender typically takes four to eight weeks from application to completion, depending on the valuation and the legal work. A further advance with your existing lender can be quicker. Many lenders let you secure a new deal up to six months before your current one ends, so it pays to start early.
Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home. Alexander Southwell Mortgage Services is authorised and regulated by the Financial Conduct Authority, firm reference 1011890.


