Same Day Decisions
FCA Authorised (No. 1011890)
Access to 1,000+ Products
End-to-End Support
5-Star Rated Advisers
What Is It?

What is an agreement in principle and why do estate agents ask for one?

An agreement in principle (AIP) is a written statement from a mortgage lender saying that, based on the details you have given and a soft credit check, it would be willing to lend you a certain amount. Different lenders call it different things: a mortgage in principle, a decision in principle (DIP), a mortgage promise or an approval in principle. They all mean the same thing. It is not a guaranteed mortgage offer and it is not a full mortgage application, but it is the document that turns you from someone browsing into a buyer that estate agents and sellers take seriously. Most estate agents will ask to see one before they put your offer forward, and some will not book viewings without it. It also gives you a clear idea of your budget so you only view properties you can actually afford. Because we are a whole of market mortgage adviser, we place the agreement in principle with the lender most likely to say yes to your circumstances, rather than the one bank you happen to have a current account with, and we do it free of charge.

"Most of our agreements in principle are issued the same working day. Send us your details in the morning and you will usually have the certificate in your inbox before the estate agent closes."

Fast, Free and Simple

How long does a mortgage in principle take, and what does it cost?

With us, an agreement in principle is free and usually issued the same working day. Here is what happens and what you get.

🤝

Turnaround: usually the same working day

Send us your details through the form and a mortgage adviser will call you back, confirm a few points and submit the decision in principle to the right lender. Many lenders give an instant decision, so the certificate is often with you within a couple of hours. Applications received late in the day or over the weekend are dealt with first thing the next working day.

Cost: Free
Turnaround: same working day
Credit check: soft search only

Buying with a partner? We run the agreement in principle jointly so it reflects both incomes and both credit files, which is what the estate agent and the lender will want to see.

🏗

Credit check: soft search, no effect on your credit score

Almost every lender we use runs a soft credit search for a decision in principle. It lets them see your credit history at the credit reference agencies without leaving a footprint that other lenders can see, so it does not affect your credit score. A hard credit check only happens later, when you make the full mortgage application.

Worried about missed payments or a thin credit file? Tell us before we apply. We will choose a lender whose criteria fit rather than let a decline sit on your record.

You are welcome to apply online with a bank directly, but a bank can only check its own criteria. We check the whole market first, so the agreement in principle you show the estate agent is one that will actually turn into a mortgage offer.

🏘

Valid for: 60 to 90 days, refreshed free

Most agreements in principle last 60 to 90 days depending on the lender, which is plenty of time to view properties and have an offer accepted. If your property search runs longer, or your financial circumstances change, we simply refresh it for you. There is no charge and no pressure to proceed.

What Your Agreement in Principle Includes

You receive a certificate from the lender confirming how much you could borrow, based on your income, outgoings and credit report. It is not tied to a specific property, so you can use it for any home within that budget.

Alongside it we give you a rough idea of the monthly payments at today's mortgage deals, so you know what the loan will actually cost, not just how much you can borrow.Why it matters: an agreement in principle from a whole of market broker carries more weight with estate agents than one printed from a comparison site, because they know the affordability has been checked properly and the full application is far more likely to go through.

Why Bother?

Why do I need an agreement in principle before I view properties?

Strictly speaking you do not, but buying without one is like going to an auction without knowing your limit. Here is what it does for you.

Four good reasons

First, it makes you a serious buyer. Estate agents are paid on completions, so when two offers land they push the one with an agreement in principle attached. Second, it stops you falling in love with a house you cannot afford, because you know your budget before you start searching. Third, it flushes out problems early: if there is something on your credit file or an income the lender will not count, better to know now than after your offer is accepted. Fourth, it speeds up the full mortgage application later, because the lender already has your key details on file and the mortgage decision has effectively been made once. For first time buyers and people moving home alike, it is the single most useful thing you can do before viewing.

From AIP to Keys

Agreement in principle vs mortgage offer: the four steps in between

People often ask how a mortgage in principle and a mortgage offer differ. The short answer is that the agreement in principle is the lender saying "probably yes" based on your details, and the formal mortgage offer is the lender saying "definitely yes" to a specific property after a full application, a hard credit check and a valuation. Here is how you get from one to the other, and where we do the heavy lifting.

WRITTEN BY

Mr Jamie Alexander, CeMAP qualified mortgage adviser and founder of Alexander Southwell Mortgage Services

FCA authorised, reference number 1011890. Jamie has over 20 years' experience in residential and buy to let lending and has arranged thousands of agreements in principle for first time buyers, home movers and landlords across the UK. Page last reviewed September 2026.

1

Step 1: Agreement in principle (same day)

You give us your income, outgoings, deposit and address history. We run a soft credit check with the lender that best fits and you receive the AIP certificate, usually within hours.

2

Step 2: Property search and offer accepted

You view properties within your budget and make an offer with the certificate attached. Estate agents take it seriously, and if the seller wants proof of funds this is what they mean.

3

Step 3: Full mortgage application

Once your offer is accepted we submit the full application to the lender with your supporting documents: payslips or accounts, bank statements and ID. This is when the hard credit check happens and the valuation is booked.

4

Step 4: Formal mortgage offer

The lender issues the official mortgage offer, normally valid for three to six months, and your solicitor can exchange contracts. From accepted offer to mortgage offer typically takes two to four weeks with a well packaged application.

Decorative line pattern behind the agreement in principle steps
HOW TO APPLY

How to get a mortgage in principle with us, usually the same day

You can apply online through the form at the top of this page or simply give us a call on 03300 432 428. Either way, the process is quick, and nothing about it commits you to using us for the mortgage itself.

Applying online for a mortgage in principle on a laptop at the kitchen table
1

Step 1: Tell us a little about yourself

Fill in the short form or call us. We need your name, date of birth, three years of address history, your income and roughly what you spend each month on loans, cards and other commitments. It takes about ten minutes.

2

Step 2: A quick chat with a mortgage adviser

One of our advisers calls you back to check the details, ask about the deposit and the type of property, and work out how much you could borrow across the market. This is also where we spot anything a lender might question.

3

Step 3: We submit the decision in principle

We choose the lender whose criteria match your circumstances and submit the DIP. Most lenders run a soft credit search and give a decision instantly or within the hour. If one lender says no, we know why and can go to another without a mark on your credit file.

4

Step 4: Your certificate lands in your inbox

You get the agreement in principle certificate to show estate agents, along with a note of the likely monthly payments and the deposit needed. Apply before mid afternoon on a working day and it is usually with you the same day. Weekends and bank holidays roll to the next working morning.

WHAT LENDERS CHECK

What does a lender check for a decision in principle?

A decision in principle is a light touch version of the full affordability assessment. The lender is not yet verifying documents, but it is checking the same six things it will look at properly later, so it pays to get them right first time.

Income and Employment

Basic salary, overtime, bonuses and, for the self employed, your last one to three years of accounts. Most lenders will lend around 4.5 times income, some up to 5.5 times for the right profile. Self employed? See ourself employed mortgages page for how lenders read your accounts.

Credit History and Credit Score

The soft credit search shows the lender your credit history at the credit reference agencies: missed payments, defaults, the number of accounts you hold and how you manage them. A good credit rating widens your choice of mortgage deals. It helps to look at your owncredit report before you apply, and if there is something on it, read our guide to improving your credit score for a mortgage.

Financial Commitments

Loans, credit cards, car finance, childcare and maintenance all come off your income before the lender works out what you can borrow. Clearing a small loan before you apply can add thousands to the maximum.

Deposit and Loan to Value

How much deposit you have and where it comes from. Savings, a gift from family, equity from a sale and Lifetime ISAs are all fine. The bigger the deposit as a share of the property value, the better the interest rate and the more lenders will consider you.

Address History and ID

Lenders want three years of address history and to confirm you are on the electoral roll. Gaps, recent moves or an address the credit file does not recognise are the most common reason a decision in principle bounces, and the easiest to fix.

Age, Term and Monthly Payments

Your age sets the longest mortgage term available, and the term changes the monthly mortgage repayments the lender tests you against. A longer term lowers the payment and can increase the amount you can borrow, at the cost of more interest overall.

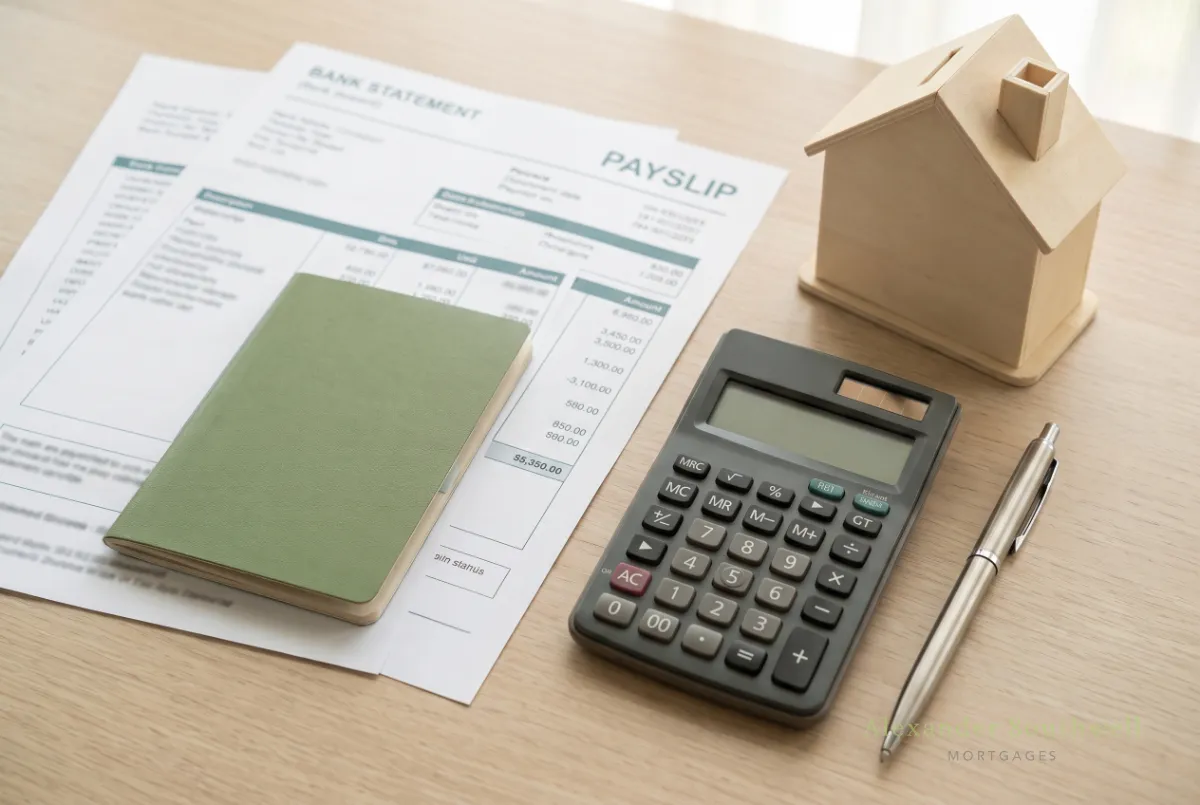
Payslips, bank statements and a calculator, the details a lender checks for a decision in principle

Want a rough figure before you apply? Try ourmortgage affordability calculator for an instant estimate of how much you could borrow, then let us confirm the real figure with a lender the same day.

Have These Ready

What you need to apply for a mortgage in principle

You do not need to send documents for the agreement in principle itself, just accurate information. Have these five things to hand and the whole thing takes about ten minutes. The supporting documents come later at full application.

AIP, DIP OR MORTGAGE OFFER?

Agreement in principle, decision in principle or mortgage promise: what is the difference?

The mortgage market has never agreed on one name, which is why this confuses people. Here is what each term means and how it compares with the documents that come later.

Hand holding new house keys at a green front door after the mortgage offer completes

Agreement in Principle (AIP)

The most common name. A lender's written indication of how much it would lend based on your details and a soft credit check. Free, quick and not binding on either side.

Decision in Principle (DIP) and Mortgage Promise

Exactly the same thing under a different label. Some lenders say decision in principle, Nationwide and a few others call theirs a mortgage promise, and comparison sites often say mortgage in principle. Estate agents accept any of them.

Formal Mortgage Offer

The official mortgage offer comes after a full mortgage application, a hard credit check, verified documents and a valuation of the chosen property. This one is binding on the lender, subject to nothing changing before completion.

Is an agreement in principle guaranteed?

No. It is a strong indication, not a guaranteed mortgage offer. It can fall away if your income or credit file turn out different from what you declared, if the property does not value up, or if the lender changes its criteria. That is exactly why we check your details properly first, so the AIP we issue is one that holds.

AFTER YOUR AIP

What happens after your agreement in principle?

The certificate is the start, not the finish. Here is how to use it well, and what to do if your plans change along the way.

Start viewing with confidence

Register with estate agents and tell them you have an agreement in principle in place. Keep your search inside the figure on the certificate, with a little room for stamp duty, legal fees and moving costs.

Offer accepted? Call us the same day

We turn the AIP into a full mortgage application, choose the best mortgage deal for that specific property and chase it through to offer. First time buyer? Ourfirst time buyer mortgages page explains the rest of the journey. Moving? See moving home mortgages.

If your circumstances change

New job, bigger deposit, a new loan or a change in the property you want: tell us and we will refresh the agreement in principle, with the same lender or a different one if that now suits you better. It costs nothing.

If it expires before you find a home

Agreements in principle last 60 to 90 days. If your property search runs past that, we renew it, again with a soft search, so there is no impact on your credit rating. Plenty of clients go through two or three before they find the right mortgage and the right house.

Mortgage Affordability Calculator

A rough idea of how much you could borrow and what the monthly payments might look like. Your agreement in principle confirms the real figure with a lender.

For illustration only, not financial advice and not a guarantee of borrowing. Lenders each apply their own affordability rules and interest rates, so your true figure can differ. Get an agreement in principle for an accurate answer.

Ready to apply for a mortgage? Get your free agreement in principle today, usually within hours.
Call 03300 432 428

Your home may be repossessed if you do not keep up repayments on your mortgage. An agreement in principle is not a guarantee that a mortgage will be offered.

FAQ

Agreement in Principle FAQs

First time buyers on a sofa checking their agreement in principle on a tabletDecorative line pattern behind the agreement in principle FAQs

How long does it take to get an agreement in principle?

Does a mortgage in principle affect your credit score?

Is an agreement in principle free?

How long does a mortgage in principle last?

Is a mortgage in principle the same as a decision in principle?

Can I get a mortgage in principle online?

Do I need an agreement in principle before viewing properties?

What if my agreement in principle is declined?

How much could I borrow on a mortgage in principle?